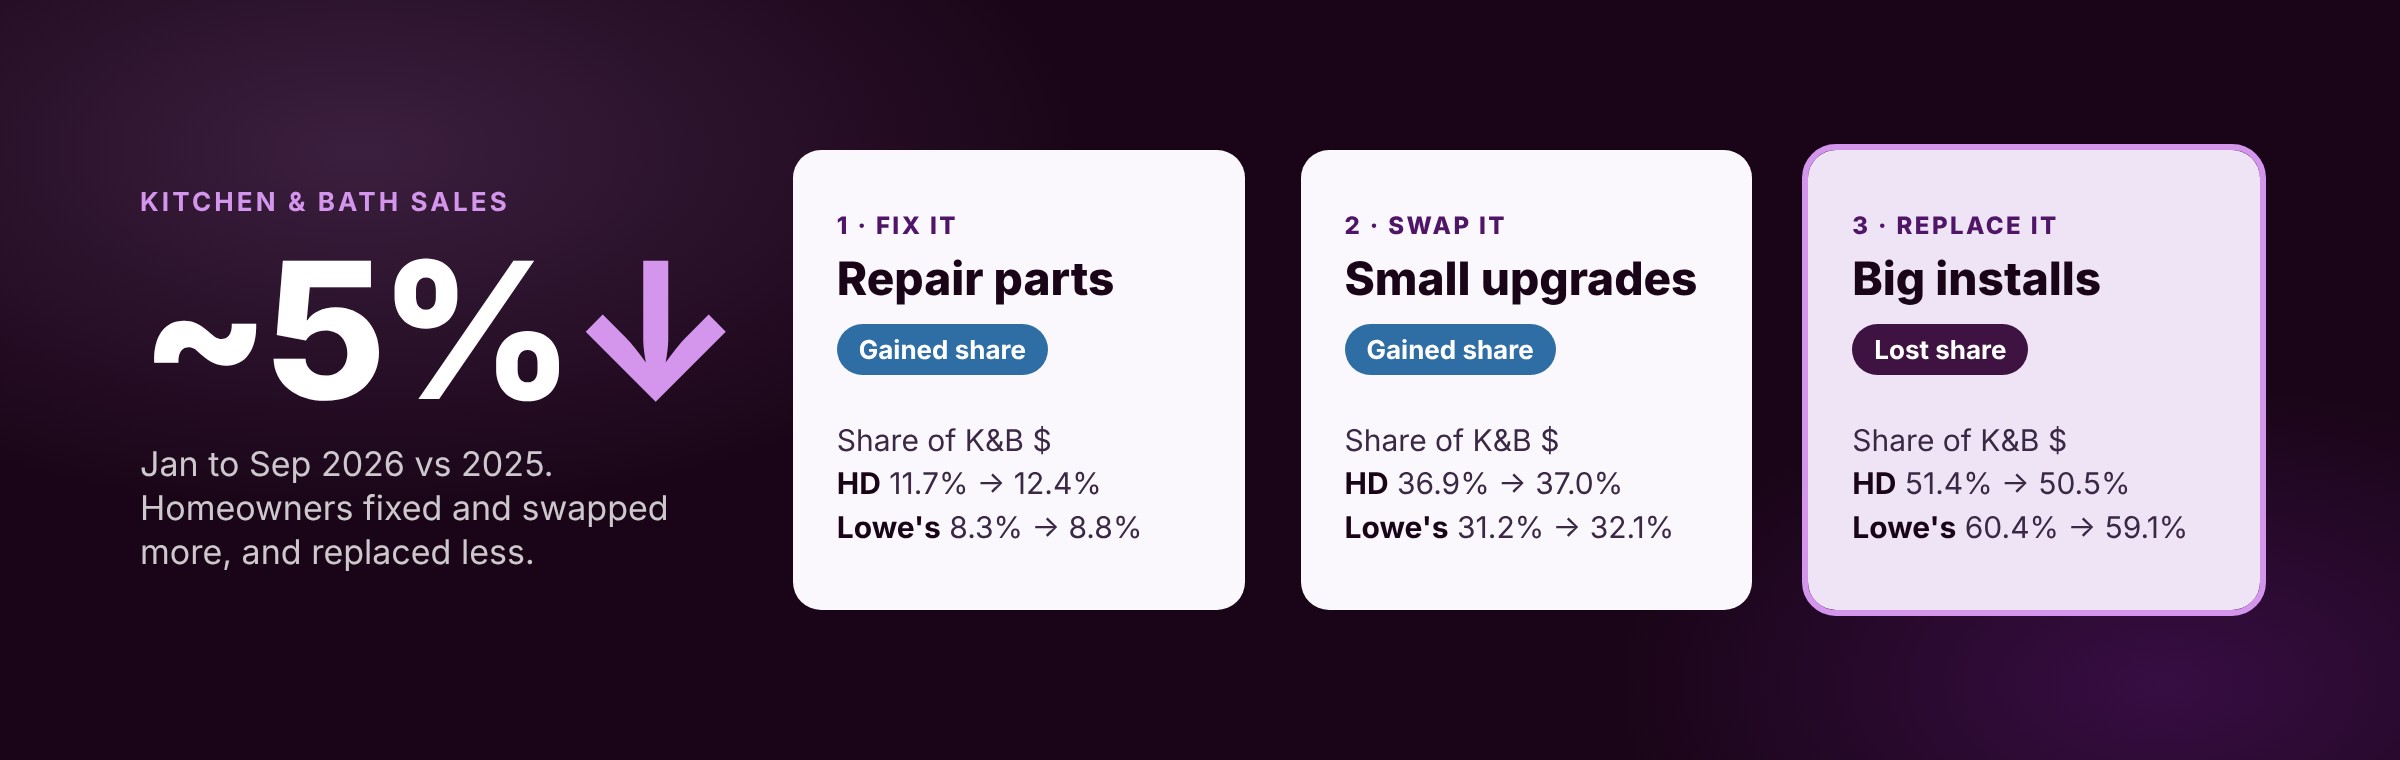
Kitchen and bath sales at Home Depot and Lowe's fell about 5% in the first nine months of 2026. The drop was not even. Repair parts and small upgrades gained share of kitchen and bath dollars, while big installs like toilets, tubs and vanities lost share. Homeowners are still spending. They are fixing and swapping more, and replacing less.
These findings come from our October 28, 2026 webinar with Green Builder Media and Kohler, presented by Alec De Jong, Senior Customer Solutions Manager at Datavations. The full recording is below, and on the webinar page.
Why is renovation the story in 2026?
Existing home sales rose 2% from December 2024 to August 2026, measured as a rolling 12-month total (Redfin). Single-family new construction permits fell 9% over the same period (Census Bureau). Fewer new builds and steady sales of existing homes mean more houses that need work.
How did we measure kitchen and bath spending?
We analyzed 111 kitchen and bath categories: 58 at Home Depot and 53 at Lowe's. We compared January through September 2026 with the same months of 2025, using Datavations point-of-sale data down to the SKU, category and state. Every SKU went into one of three buckets, based on how much work the homeowner takes on:
- Fix it: repair parts, such as fill valves, flappers and cartridges.
- Swap it: small upgrades, such as faucets, showerheads and towel bars.
- Replace it: big installs, such as toilets, tubs, showers, sinks and vanities.
These are the categories analyzed for this report, not total kitchen and bath at either retailer.
Which kitchen and bath segments held up best?
Fix it held up best. Repair sales rose 1.6% at Home Depot and 0.4% at Lowe's, while total kitchen and bath fell 4.0% and 5.3%. Repair's share of kitchen and bath dollars grew from 11.7% to 12.4% at Home Depot and from 8.3% to 8.8% at Lowe's.
A simple ratio shows the shift: repair parts sold for every 100 big-ticket units. From June to September 2026, that ratio rose 7.5% at Home Depot and 6.0% at Lowe's versus the same months of 2025. That is what it looks like when homeowners replace the fill valve instead of the whole toilet.

What happened to small upgrades like faucets?
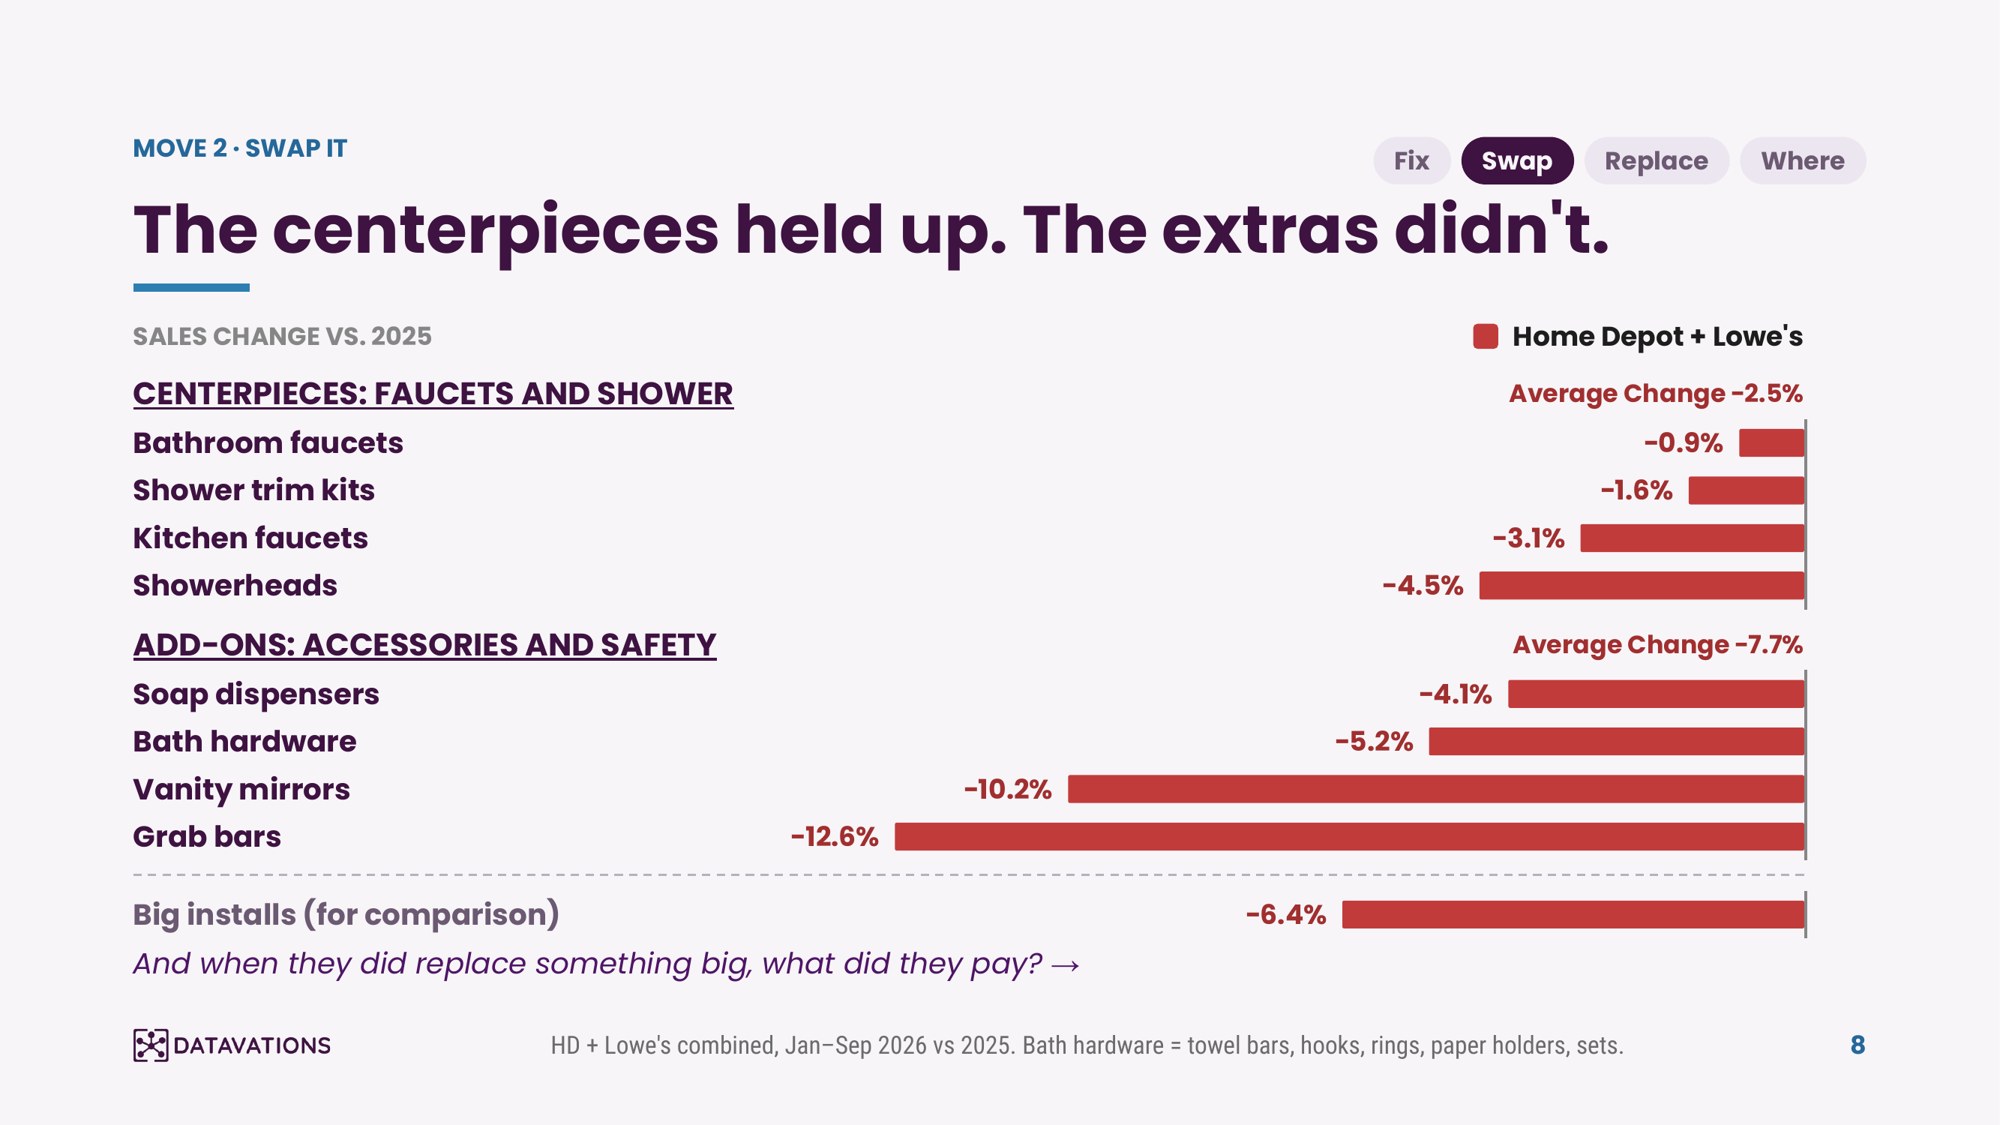
Swap it sales fell 3.6% at Home Depot and 2.7% at Lowe's, but the bucket still gained share at both. Across both retailers combined, the centerpieces held up. Bathroom faucets fell 0.9%, shower trim kits 1.6%, kitchen faucets 3.1% and showerheads 4.5%, for an average of 2.5%.
The extras fell harder. Soap dispensers fell 4.1%, bath hardware 5.2%, vanity mirrors 10.2% and grab bars 12.6%, for an average of 7.7%. For comparison, big installs fell 6.4%.
How did big installs and pricing change?
Replace it took the biggest hit. Sales fell 5.6% at Home Depot and 7.4% at Lowe's, and units fell 9.0% and 9.9%. Big installs are still more than half of kitchen and bath dollars at both retailers, but their share slipped from 51.4% to 50.5% at Home Depot and from 60.4% to 59.1% at Lowe's.
Shoppers who did replace paid more. The average price per big-install item rose 3.3%. Units also moved to the ends of the price range. The entry price band grew from 15.6% to 20.7% of big-install units, premium held flat at about 28%, and the two middle bands shrank. Seven new store-brand toilets made up 41% of entry-band units. Even so, store-brand share of two-piece toilet units fell from 53.2% to 51.1%. A lower price alone did not win share.
Where did homeowners pull back the most?
Big-install sales fell 6.4% nationally across both retailers, and the coasts pulled back hardest. Maine fell 10.9%, Florida 9.4% and Maryland 9.1%. Connecticut, Delaware and New Jersey each fell 8.3%. Hawaii grew 1.1%, and Alaska, Wisconsin and Nebraska each fell less than 1%.

What should kitchen and bath manufacturers plan for in 2027?
We see four priorities, one for each part of the story:
- Fix it: keep the parts on the shelf. Repair is gaining on replacement, and the part that is in stock keeps your brand in the home.
- Swap it: win the afternoon project. Faucets carried the bucket, so make the easy upgrade easy to find and easy to choose.
- Replace it: win on value, not price. Shoppers paid more per item, and cheaper store-brand toilets did not gain share.
- Where: watch the coasts. They pulled back hardest in 2026.
None of this is a forecast. It is what the shelf shows right now. Datavations builds this view from SKU-level point-of-sale data across retailers, so your next merchant conversation starts with the facts, not a guess.
Frequently Asked Questions
Are kitchen and bath sales down in 2026?
Yes. Across the 111 kitchen and bath categories Datavations analyzed, sales fell 4.0% at Home Depot and 5.3% at Lowe's from January to September 2026 versus 2025. Most of the drop came from big installs.
Are homeowners repairing fixtures instead of replacing them?
The data points that way. Repair parts sold for every 100 big-ticket units rose 7.5% at Home Depot and 6.0% at Lowe's from June to September 2026. Big-install units fell about 9% to 10% at both retailers over the first nine months.
Which bathroom products held up best in 2026?
Faucets and shower trim held up best. Bathroom faucets fell only 0.9% across Home Depot and Lowe's combined. Vanity mirrors and grab bars each fell more than 10%.
Which states saw the biggest drop in kitchen and bath spending?
Big-install sales fell most on the coasts. Maine fell 10.9%, Florida 9.4% and Maryland 9.1%. Hawaii was up 1.1%.
Want this view for your own categories? Sign up for Pulse, our free monthly report. Every SKU. Every store. Every sale.